Multihead
← BACK140 Factors → 14 Heads → Market-Neutral Portfolio
STORY
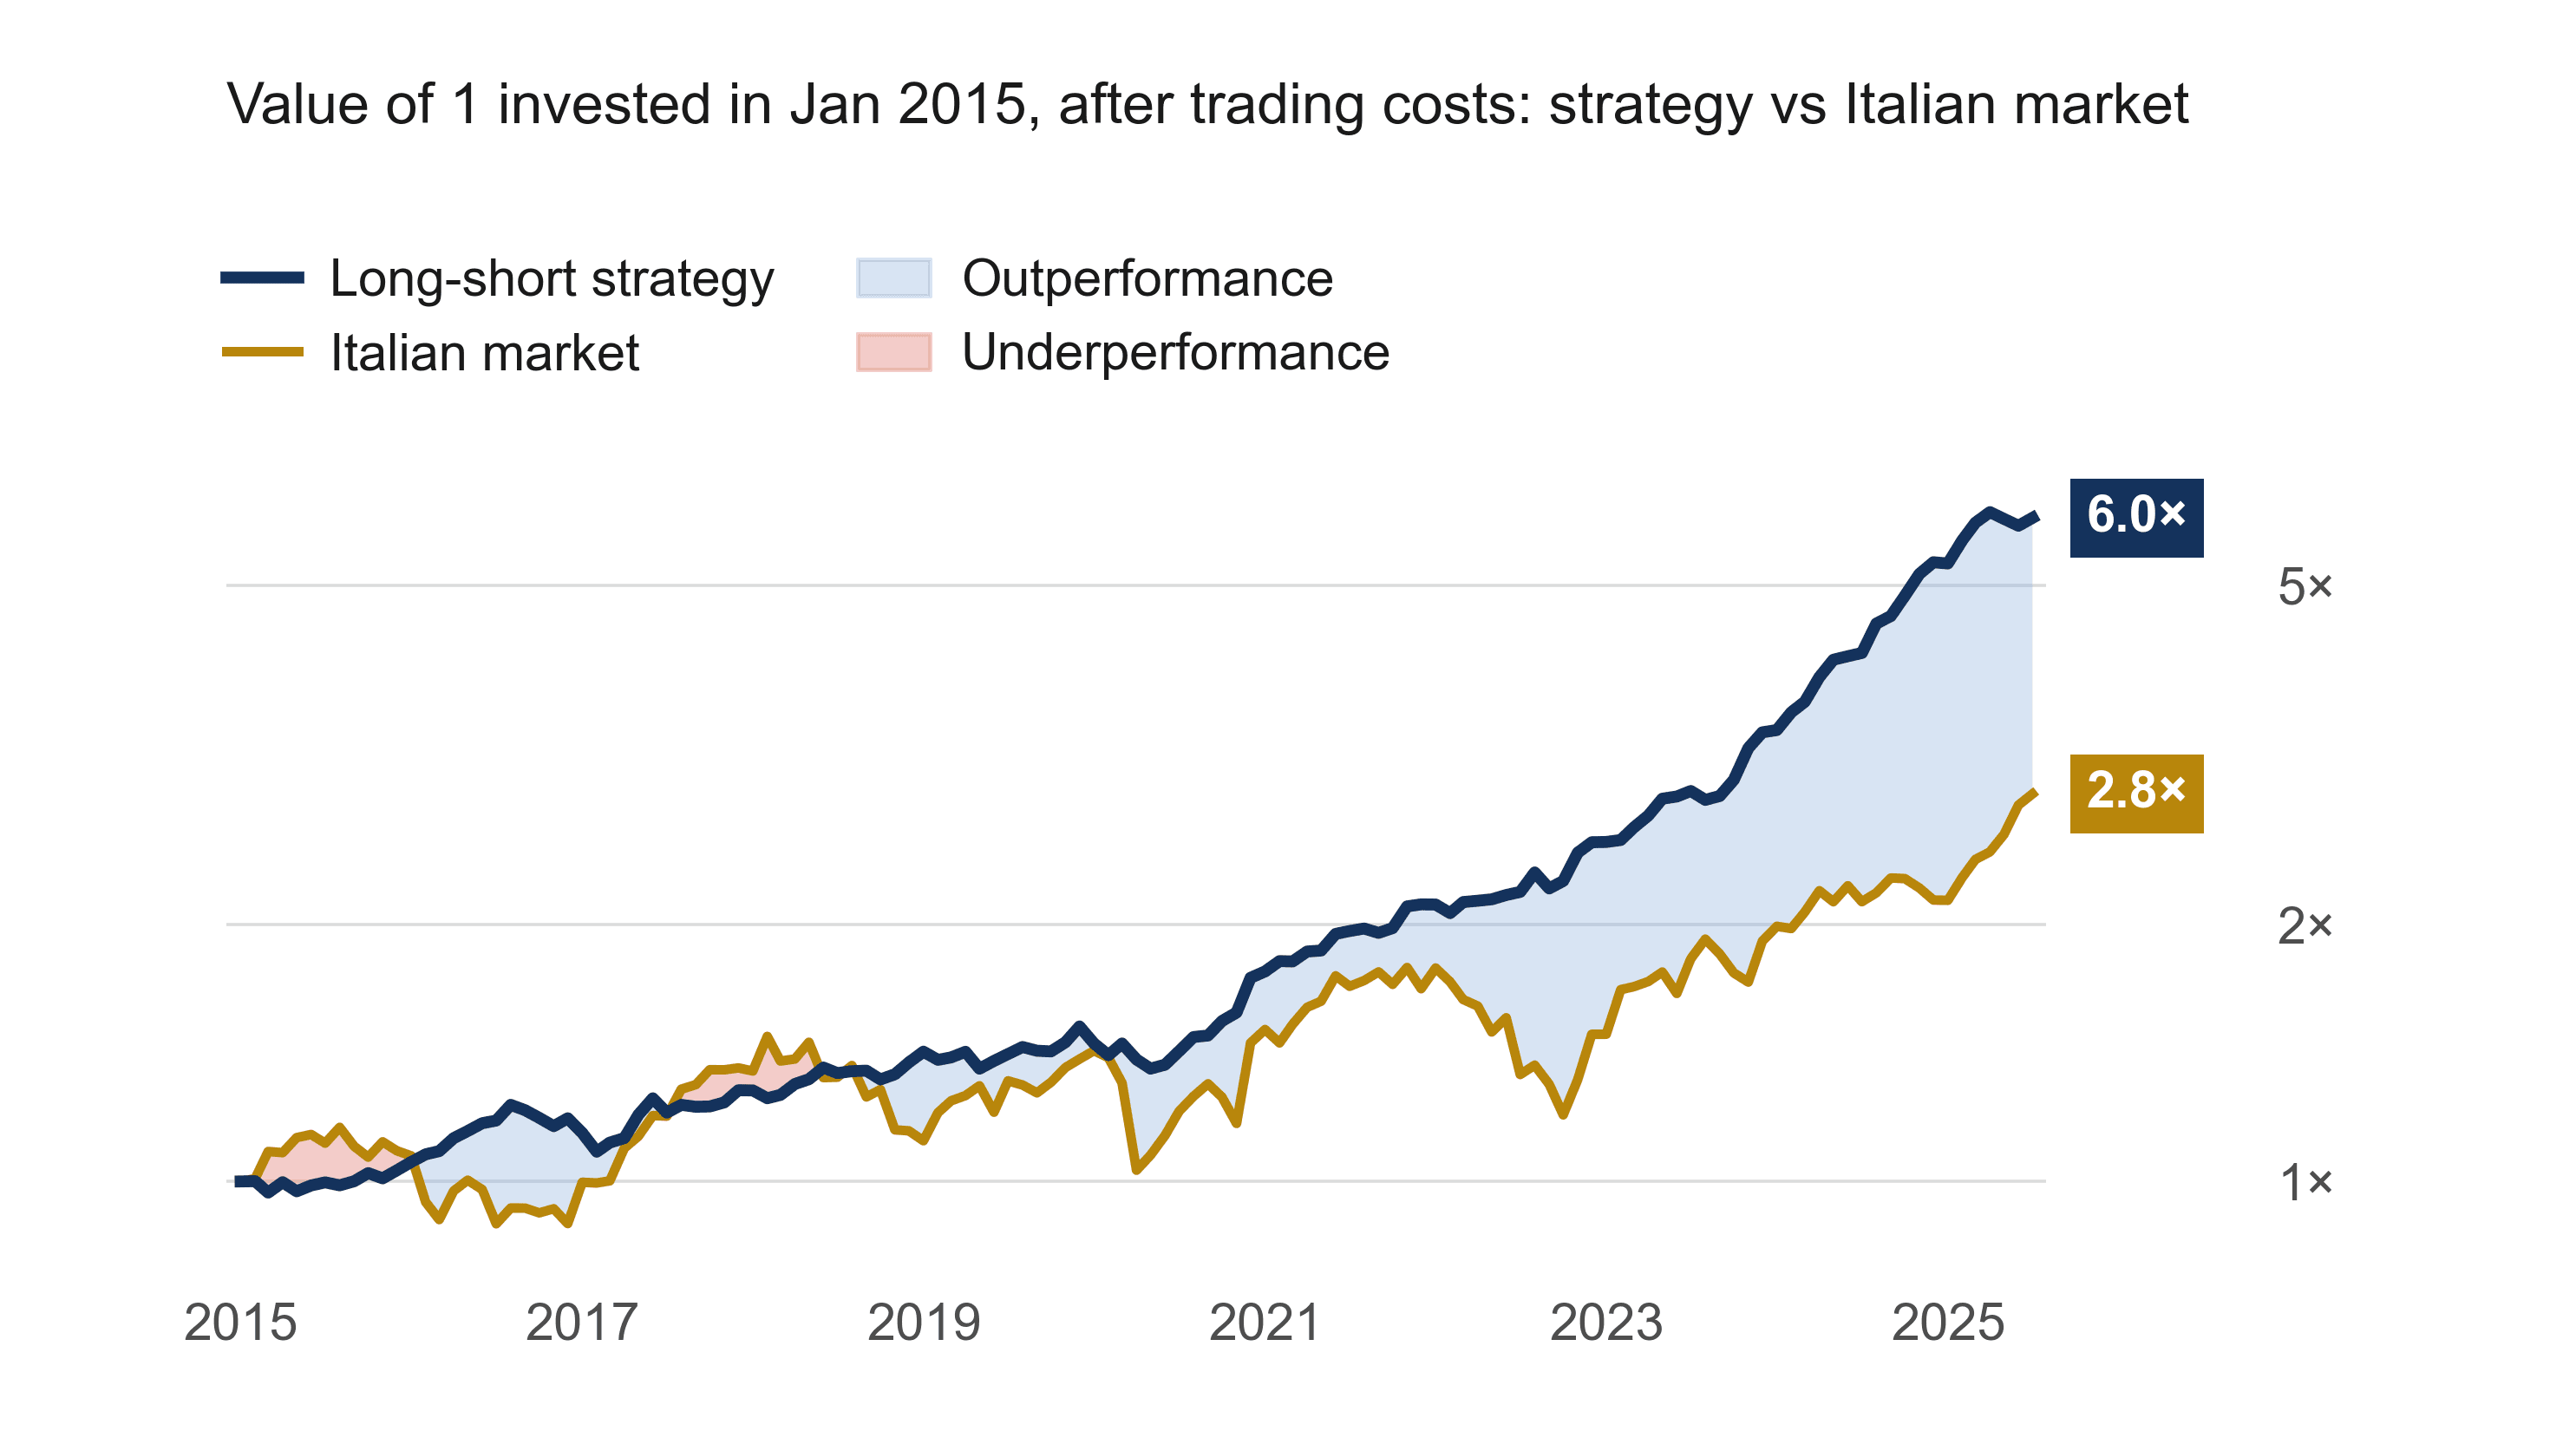
Built a quantitative trading strategy that uses a neural network to pick Italian stocks. The model reads 140 company characteristics over 20 years of monthly data, split into 14 families (momentum, value, risk…). Each family has its own small layer; their outputs are joined and passed through two shared layers of 64 and 32 neurons, ending in one return forecast per stock. Retrained every 6 months on past data only. Each month it buys the top 100 stocks and shorts the bottom 100.
TECHNOLOGIES
- Python
- PyTorch
- pandas